Know who to lend to before you lend.
Highlend grades every loan application on repayment history, affordability, collateral and credit bureau data. Your officer gets a clear recommendation, the reasons behind it and the most you should lend. Then Highlend runs the loan, the collections, the payments and the books.
Lending operations, decisioning and books in one place.
Highlend gives licensed lenders the full loan lifecycle — appraisal, disbursement, repayment and the ledger behind all of it.
What's behind the grade
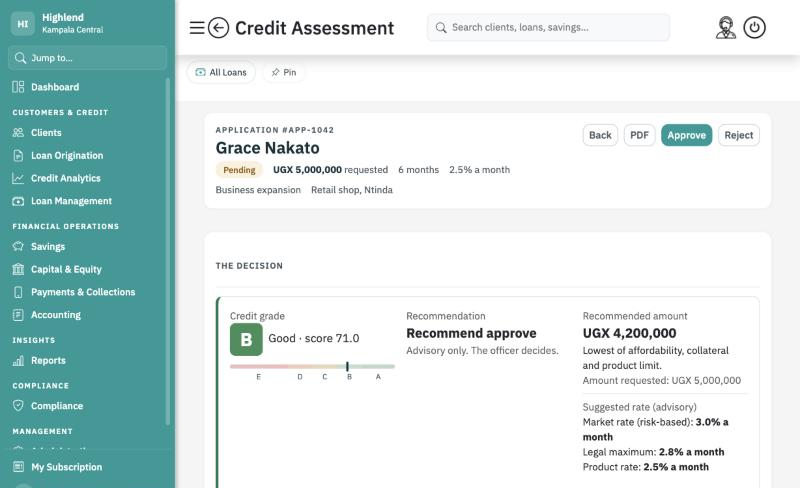
Each application gets a score out of 100. The five parts of the score, and the reason for each, sit right under the recommendation, so an officer can check every point before deciding.
The recommended amount is the lowest of what the borrower can afford, what the collateral covers and your product limit.
- Repayment history28 / 353 loans repaid, worst delay 12 days
- Affordability17 / 25Debt-to-income 31%, within the 40% limit
- Collateral12 / 15Logbook covers 1.6× the loan
- Credit bureau8 / 151 adverse account in the last 12 months
- Relationship6 / 10Client for 2 years
One grade, built from five things you can check
Every point in the score comes from a figure on the application, so your officers can see exactly why an applicant got the grade they did.
Repayment history
How the borrower has repaid loans with you: days late, defaults and refinancing.
Affordability
Income against existing debt, including instalments reported by the bureau.
Collateral
Valued security against the amount asked for, with forced-sale cover.
Credit bureau
Adverse accounts and probability of default from Metropol, plus Airtel mobile credit data.
Relationship
How long the borrower has been your client and how they have dealt with you.
Recommend approve
A strong grade with nothing that needs a second look.
Review
Debt above 40% of income, a stale bureau report or too little collateral sends it to an officer.
Recommend decline
A borrower who has been 91 days or more behind with you.
Bureau checks from inside the application
Pull a Metropol credit report or Airtel mobile credit data while you assess the loan. The results go straight into the grade, so nobody retypes figures from a PDF.
Every check needs the borrower's signed consent and a copy of their National ID, reviewed before the request goes out.
- Metropol credit score, payment behaviour and existing instalments
- Airtel mobile credit data through gnuGrid
- Signed consent and ID reviewed before every check
- The full Metropol report when you need the document itself
A credit memo your committee can read
Ask for a written memo on any assessment. It explains the grade in plain words, points out figures that contradict each other and lists what the officer should check before deciding.
It never sees names, ID numbers or phone numbers, and it never makes the decision.
Credit memo
Strong repayment record with this lender: three loans closed, none more than 12 days late. Affordability is comfortable at 31% of declared income.
Declared monthly income is about 40% higher than the deposits in the bank statement. Confirm the second income source before disbursing.
The bureau shows one adverse account, closed in March. Ask the borrower how it was settled.
The officer records the decision and the reason.
Everything else a lender runs on
Approved loans move straight into the rest of Highlend, so the schedule, the collections and the books all work from the same figures.
Clients and origination
Bring borrowers in and move applications to a decision.
- Individual, group and institution clients
- Leads pipeline for prospects
- Import existing clients and loans from spreadsheets
- Loan products with your own rates, fees and penalties
- Loan calculator for quotes
- Approval of funds, with a second approver if you want one
Loans
Every loan from payout to the final shilling.
- Flat rate, declining balance or equal-instalment schedules
- Disbursements and top-ups
- Repayments split into principal, interest and penalties
- Overpayments held as customer credit until used or refunded
- Penalties on your terms, with approved waivers
- Client statements for every loan
Collections
Know who is late and follow up until it is settled.
- Overdue and defaulted loans by days past due
- Risk classes from performing to loss
- Follow-up stages from first call to legal demand
- Promises to pay and field visits logged
- Automatic SMS reminders to borrowers
Mobile money
Pay out and collect without leaving Highlend.
- Loan payouts to mobile money, with approval before money moves
- Repayment requests sent to the borrower's phone
- Incoming payments matched to the right loan
- Wallet top-ups, withdrawals and float reconciliation
Savings
Run savings alongside lending.
- Individual and group savings accounts
- Deposits, withdrawals and term deposits
- Loans to savers
- Savings statements and reports
Accounting
Your books update as the business runs.
- General ledger and chart of accounts
- Cash and bank accounts
- Trial balance, income statement, balance sheet and cash flow
- Tax
- Investors, owner investments and retained earnings
Reports
See how the portfolio is doing at any moment.
- Dashboard of portfolio, arrears and interest earned
- Portfolio and risk reports
- Loan, repayment and disbursement reports
- Export to spreadsheet
Controls
The checks a regulator and your auditors expect.
- AML screening of clients
- Two-person approval for write-offs, reversals and manual journals
- Users, roles and permissions by branch
- A full audit log of who changed what